Informed Trading Detection Framework
A structured path from market fundamentals to advanced informed signal detection
Our team built this framework in a deliberate sequence — each module builds on the last,
moving from the mechanics of order flow to the statistical models used to identify
informed activity in live markets.
Most retail analysts encounter high-frequency data without a framework for reading it.
Our methodology starts at the mechanism level — how markets match orders, how liquidity
forms, and where informed traders leave measurable traces — then advances through
quantitative detection methods used in institutional research.
- Progress from microstructure fundamentals to multi-market signal synthesis at your own pace
- Each module is anchored to a documented real-market case study, not a theoretical scenario
- Detection logic is explained step by step, so the methodology can be applied and adapted independently
Signal detection rate
↑ 38 bps
Informed order flow identified ahead of price adjustment in documented case study
Full transparency
$0 black-box
Three tracks within the detection framework
The framework is structured into three progressive tracks, each designed for a different level
of prior analytical experience — from foundational concepts to advanced quantitative modeling.
Contact
for access details
Designed for analytically curious investors who are new to market microstructure and
want to build a rigorous foundation before engaging with detection models.
- Introduction to limit-order book mechanics
- Documented case studies from Australian equity markets
Basics of trade direction classification
Volume and liquidity pattern reading
Understanding bid-ask spread dynamics
Identifying uninformed versus directional flow
Popular
Practitioner Track
Contact
for track details
Built for analysts and investors who already understand market structure and want to apply statistical methods to detect informed trading signals in real order-flow data.
- Probability of Informed Trading models
- Order flow imbalance measurement techniques
- Volume-synchronized probability of informed trading
- Multi-asset signal comparison methodology
Supervised classification of trade sequences
Anomaly detection across intraday volume profiles
Real-market episode analysis with worked examples
Advanced Mastery Track
Contact
for mastery details
For experienced quantitative analysts seeking to synthesize detection signals across
multiple markets and integrate machine learning pipelines into their own research
process.
Cross-market informed flow synthesis models
Constructing and back-testing detection screens
Interpreting signal degradation and model limitations
Community research contribution and peer review
The full curriculum path, module by module
Eight sequential modules take the analyst from market microstructure basics through to advanced multi-market informed signal synthesis — each building directly on the last.
1
Module One and Two: Market Microstructure and Order Flow Foundations
The first two modules establish the mechanical foundation. Module One covers how modern electronic markets match orders, how the limit-order book forms and evolves, and what the bid-ask spread actually measures. Module Two introduces order flow — how directional trades differ from liquidity-providing trades, and why that distinction is the starting point for any detection methodology. Both modules are anchored to documented real-market episodes from Australian and international equity venues, so the mechanics are always shown in context rather than described in isolation.
2
Module Three and Four: Measuring Informed Activity Statistically
Module Three introduces the Probability of Informed Trading model — its assumptions, its construction from trade and quote data, and its documented limitations in modern high-frequency environments. Module Four extends this to Volume-Synchronized Probability of Informed Trading, a methodology better suited to contemporary markets where trade arrival rates vary significantly across the session. Our team presents both methods with full worked examples, discussing where each measure performs well and where signal quality tends to degrade under specific liquidity conditions.
3
Module Five: Supervised Classification of Trade Direction and Sequence
This module applies machine learning classification methods to the problem of inferring trade direction and detecting informed sequences in order flow. Feature construction from tick data is covered in detail — including how to encode time, volume, and price interaction variables in a format suitable for classification algorithms. Our team documents the performance characteristics of several model families under realistic back-testing conditions, and discusses the practical trade-offs between model interpretability and predictive signal strength. All examples use historical data from documented market episodes.
4
Module Six and Seven: Anomaly Detection and Multi-Market Signal Synthesis
Module Six shifts from classification to anomaly detection — identifying volume, spread, and order-flow patterns that deviate from a statistically defined baseline in ways consistent with informed activity. Module Seven then addresses the more complex problem of synthesizing detection signals across multiple markets or instruments simultaneously, identifying cases where informed flow appears to migrate across venues or asset classes before a price event. Our team presents this as a pattern-recognition challenge with documented examples, not as a predictive exercise, and discusses the statistical caution required when interpreting cross-market signals.
5
Module Eight: Calibration, Regime Awareness, and Framework Application
The final module addresses a practical problem that the preceding modules raise: detection models calibrated on historical data behave differently when market regimes shift. This module covers signal recalibration methodology, regime identification using structural break tests, and the principles for determining when a previously reliable detection screen requires revision. Our team also presents a complete framework-application walkthrough using a documented real-market episode, demonstrating how all preceding modules connect into a coherent analytical process. The module concludes with guidance on contributing observations back to the community research loop.
Key terms across the detection framework
Market Microstructure
Foundations
The study of the processes and mechanisms through which financial assets are traded,
encompassing order matching, price formation, bid-ask spreads, and the role of
different participant types in determining transaction prices. It forms the
theoretical foundation for all informed trading detection methodologies covered in
the framework.
Order Flow
FoundationsInformed Trader
Core Concept
A market participant who trades on the basis of private or superior information
about an asset's fundamental value. Informed traders are distinguished from
liquidity traders by the directional persistence and price impact of their orders,
which leave detectable statistical patterns in order-flow and volume data.
Probability of Informed Trading
Statistical ModelVolume-Synchronized Probability of Informed Trading
Statistical ModelAn adaptation of the PIN model that synchronizes observations to volume events rather than time intervals, making it better suited to modern high-frequency markets where trade arrival rates vary substantially across the trading session. Abbreviated as VPIN, it is covered in Module Four.
Bid-Ask Spread
Foundations
The difference between the lowest price at which a seller is willing to sell and the
highest price a buyer is willing to pay at any given moment. Market makers widen
spreads in response to perceived informed order flow, making spread dynamics a
measurable indicator of information asymmetry in a market.
Order Flow Imbalance
Measurement
A metric that quantifies the net directional pressure in order flow over a defined
period, calculated as the difference between buyer-initiated and seller-initiated
volume. Persistent imbalances in one direction are statistically associated with the
presence of informed participants accumulating or distributing a position.
Dark Pool
Market StructureA private trading venue where orders are matched without pre-trade transparency, meaning neither the size nor direction of orders is visible to other market participants before execution. Informed traders may use dark pools to reduce market impact, creating detection challenges that the framework addresses in the multi-market synthesis modules.
Block Trade
Market StructureA large transaction executed outside the regular order book, typically at a negotiated price, to minimize market impact. Block trades can be a component of informed trading activity and are discussed in the framework as one of the observable events that warrant anomaly-detection scrutiny.
Unusual Options Activity
Signal DetectionAbnormal volume, open interest, or pricing patterns in options markets that deviate from statistically defined baselines in ways consistent with directional positioning ahead of a price event. The framework addresses this as a cross-asset informed trading signal in the multi-market synthesis module.
Smart Money
Core ConceptTick Data
Data SourceThe instructors and researchers behind each module in the detection framework
Each module in the framework is authored by a team member with direct research or practitioner experience in the relevant Vaslemrotuem. The team spans quantitative modeling, market microstructure theory, applied machine learning, and institutional trading practice — ensuring that no module is written at a purely academic remove from how markets actually behave.
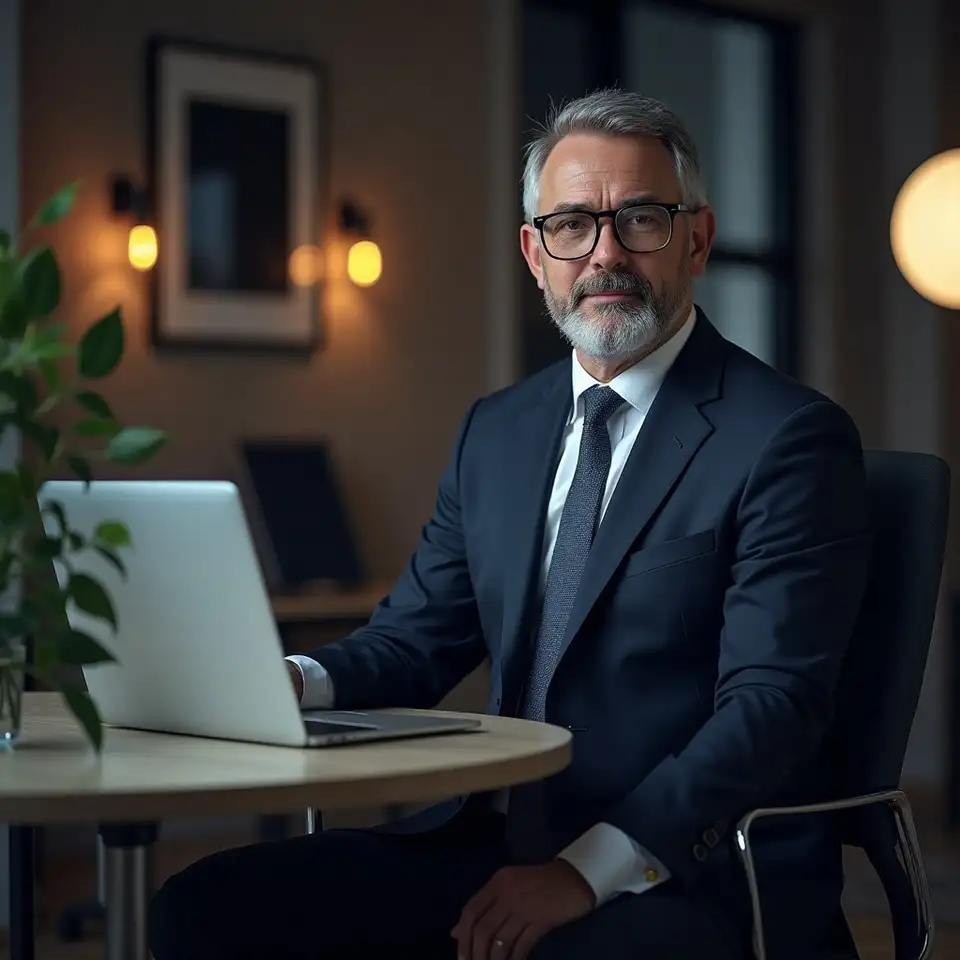
Dr. Marcus Ellery, Lead Research Analyst
Head of Market Microstructure Research
Sydney, New South Wales, Australia
Core curriculum modules authored
Market microstructure foundations, order flow measurement, PIN and VPIN statistical modeling
Primary research disciplines
Order flow toxicity and imbalance modeling
Structural informed trading detection models
Intraday liquidity pattern analysis
Marcus leads the authorship of Modules One through Four, covering the mechanical and statistical foundations of the detection framework. His decade on institutional trading desks gives him direct familiarity with how informed flow behaves in live markets — knowledge he translates into each module's case-study documentation. He also reviews all subsequent modules for internal methodological consistency before publication.
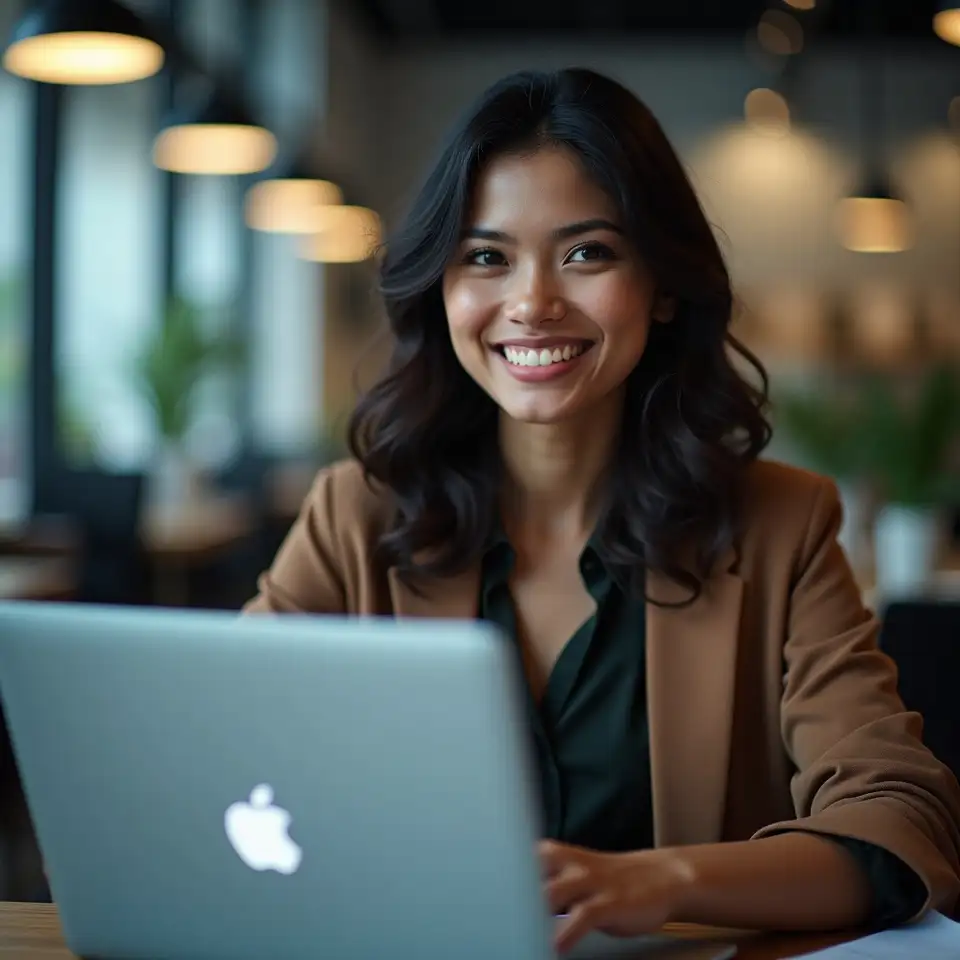
Priya Nair, Quantitative Modeling Lead
Senior Quantitative Analyst, Machine Learning Applications
Melbourne, Victoria, Australia
Modules and methods covered
Supervised classification, feature engineering from tick data, anomaly detection model construction
Technical specializations applied
Supervised classification for trade sequences
Feature engineering from high-frequency data
Anomaly detection in volume and spread profiles
Priya authors Module Five and the anomaly-detection component of Module Six. Her background in applied machine learning means she documents not just what each model does but how its performance characteristics change under realistic market conditions. She is also responsible for the back-testing methodology guidelines that run across the practitioner and advanced tracks.
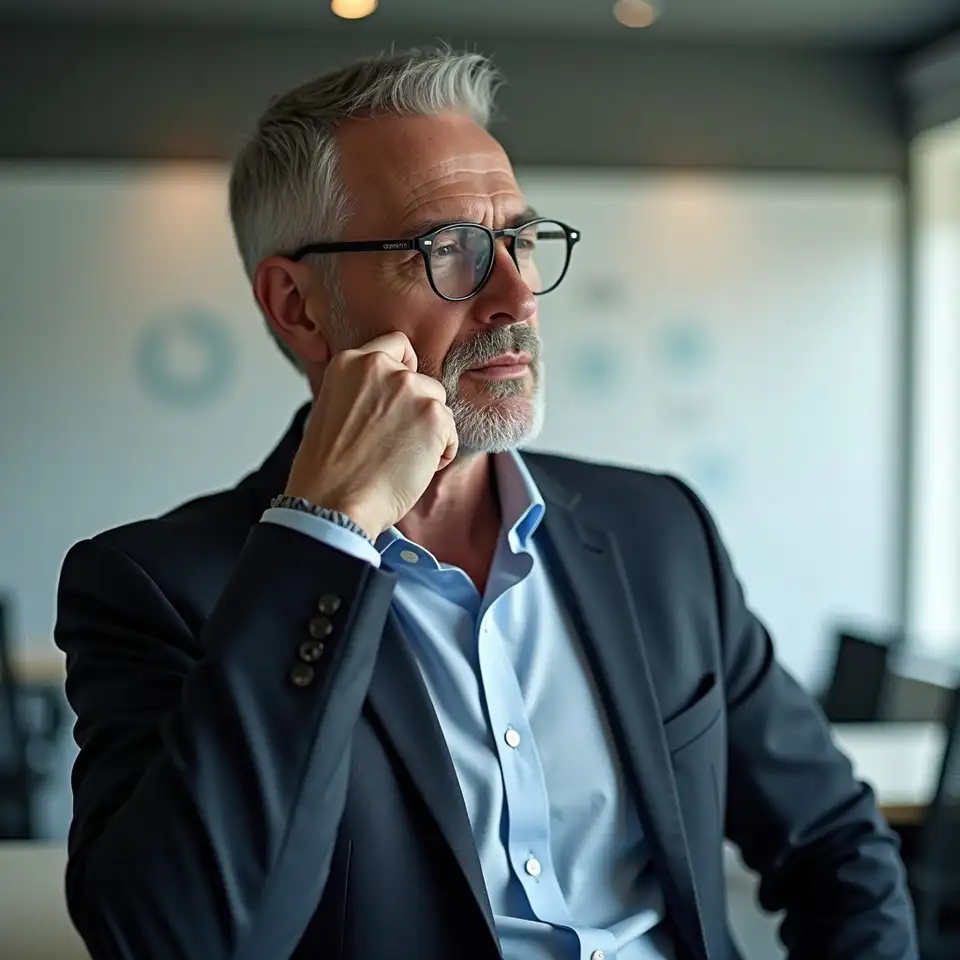
James Whitfield, Research Curriculum Director
Director of Research Documentation and Curriculum Design
Brisbane, Queensland, Australia
Documentation and structure role
Framework sequencing, case-study construction, cross-module consistency and practitioner communication
Curriculum design disciplines
Analytical framework documentation and sequencing
Real-market case study construction
Practitioner-level signal interpretation guides
James oversees the overall architecture of the eight-module sequence, ensuring that each module builds logically on the last and that the progression from foundations to advanced synthesis is coherent for analysts at different starting points. He authors the case-study narratives that anchor each module to a documented real-market episode, and reviews all published materials for clarity and precision of language.
Amelia Tan, Community and Insights Manager
Head of Community Research Insights
Perth, Western Australia, Australia
Community research and feedback role
Member observation curation, real-market anomaly integration, module revision coordination and publication management
Community engagement disciplines
Member feedback and observation integration
Research publication and revision coordination
Analytical community peer-review facilitation
Amelia manages the feedback loop between the analyst community and the authoring team. When community members identify real-market episodes that illustrate or challenge a module's detection logic, Amelia routes those observations into the review process. She coordinates all module revision cycles, ensuring published frameworks are updated when new data or structural market shifts warrant a change.
Recognition and accreditations
2024
Best Financial Education Framework
Asia-Pacific Financial Research Awards
Recognised for rigorous methodology documentation and practitioner-relevant design in quantitative market analysis research programs.
2023
Excellence in Quantitative Research Communication
Australian Investor Education Council
Awarded for outstanding clarity in translating complex statistical detection models into accessible analytical frameworks for practitioner audiences.
2022
Outstanding Microstructure Research Publication
Financial Markets Research Institute
Commended for the documented case-study approach to informed trading detection, bridging academic theory and live-market application effectively.
2024
Top Analytical Community Platform
Quantitative Analyst Network Asia
Recognised as a leading community-driven analytical research platform for serious investors applying quantitative methods to order-flow analysis.
2023
Innovation in Machine Learning Applications
Applied Finance Technology Awards
Honoured for applying supervised classification and anomaly detection techniques to real tick data within a structured and transparent research framework.
Get a free sample module
Request a sample module from the detection framework and see the methodology in practice before committing to any track. Our team will also add you to the weekly informed trading signal newsletter, delivered every Monday morning.
Email
content@vaslemrotuem.sbs
Phone
+61893364090